
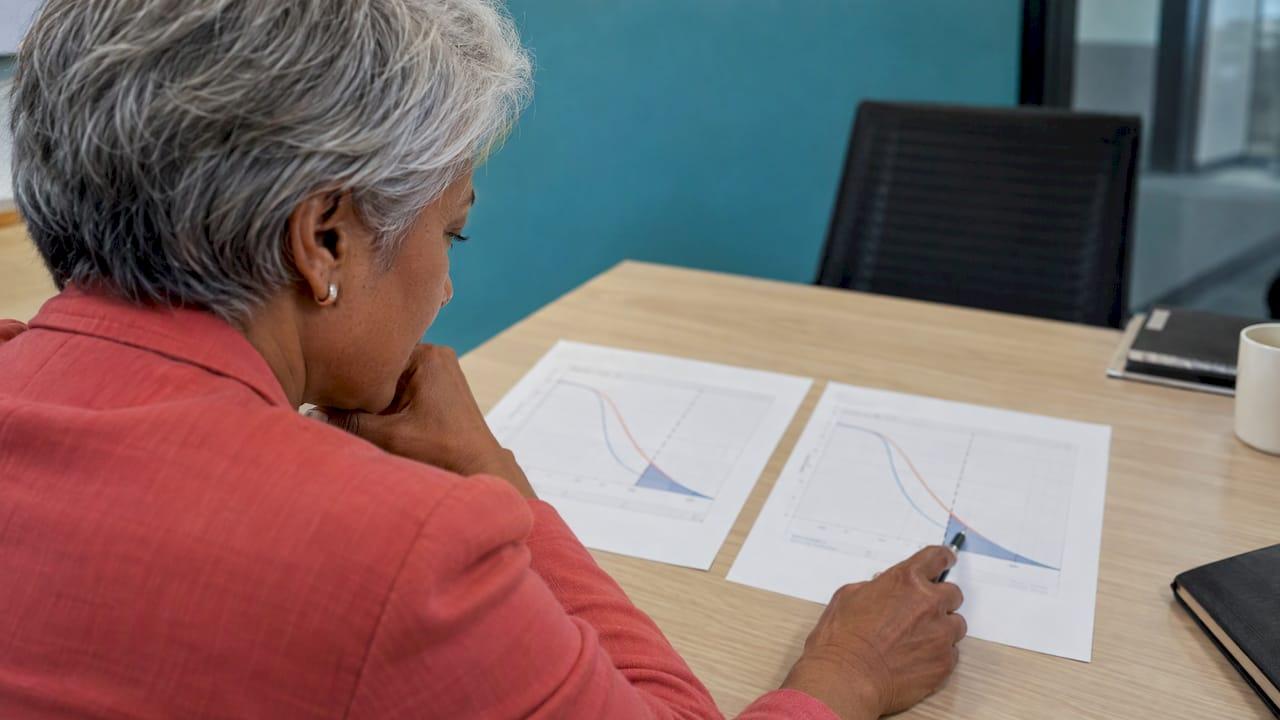
Expected shortfall (ES) answers the question Value at Risk (VaR) leaves open: when currency losses do break through your VaR limit, how bad are they on average? For a company with foreign-currency exposure, ES is the average loss across the worst slice of outcomes, for example the worst 2.5% or 1% of days, so it is always at least as large as VaR at the same confidence level. Use VaR to set the threshold and ES to size the buffer, limit or hedge that sits behind it.
This guide is for CFOs, finance directors and treasury or risk teams. It covers what ES means for an FX book, how to calculate it, a worked sterling example and what to watch for when you put it into a limit framework.
TL;DR
- Expected shortfall is the average loss in the tail beyond the VaR threshold at a chosen confidence level. VaR tells you where the tail starts, ES tells you how deep it goes.
- At the same confidence level, ES is greater than or equal to VaR. In a parametric (normal) model, the two are a fixed multiple of each other.
- For a normal distribution, ES has a closed formula: mean loss plus volatility times the normal density at the VaR point, divided by the tail probability.
- Confidence level, holding period and the quality of your volatility and correlation inputs move the number far more than the choice between VaR and ES.
- Run ES next to VaR, backtest the VaR leg, and tie both to hedge ratios and limits so the figure drives a decision.
Table of Contents
- What expected shortfall means for an FX exposure
- Expected shortfall vs VaR: the practical difference
- How to calculate FX expected shortfall
- A worked example: €1 million receivable, reporting in sterling
- The inputs that move your number most
- Limitations to know before you rely on ES
- From a number to a decision: using ES in hedging and limits
- Doing this in a spreadsheet, and where it strains
- Where Corphedge fits
- Our view
- FAQ
- Sources
What expected shortfall means for an FX exposure
Suppose your company holds a euro receivable book and reports in pounds. A one-day 99% VaR of £15,000 says that on 99 days out of 100 you should not lose more than £15,000 from exchange-rate moves. It says nothing about the 100th day. The IMF's working paper on exchange rate risk measurement makes this point directly: VaR defines a loss threshold exceeded only at a stated tail probability, and it does not describe the severity of losses beyond it.
Expected shortfall fills that gap. The Basel Committee's market risk framework summary describes ES as the average of potential losses that exceed VaR at a specified confidence level. Another IMF-linked paper on risk management defines it as the average of the worst tail losses and notes that ES is greater than or equal to VaR at the same confidence level.
You will also see ES called conditional VaR (CVaR) or tail VaR. In most corporate settings these are the same idea under different names. A few authors define them slightly differently for discrete data, so check the definition in any tool you use.

Why it matters more for currencies than it first seems
Currency returns are not perfectly bell-shaped. Central bank surprises, referendums and liquidity gaps produce days far outside what a normal curve expects. Two books can have the same VaR and very different tails: one with moves that stop just past the threshold, another with occasional gaps. ES separates them, because it averages what happens past the line rather than ignoring it.
The Basel framework is written for banks, which must hold minimum capital against market risk. A UK corporate is not bound by it, but the logic of moving from a threshold to a tail average is a useful model for internal risk limits.
Expected shortfall vs VaR: the practical difference
| VaR | Expected shortfall | |
|---|---|---|
| Question answered | What is the loss I should not exceed at X% confidence? | If I do exceed it, what is the average loss? |
| Looks at the tail? | Only its starting point | The whole tail, as an average |
| Relationship | Lower | Greater than or equal to VaR at the same confidence |
| Typical use in a company | Daily limits, alerts, backtesting | Sizing buffers, hedge ratios, stress discussions with the board |
| Backtesting | Simple: count breaches | Harder, because you compare averages of rare events |
Two things follow. First, the VaR breach count remains the cleanest way to test whether your model is behaving, which is why we treat ES as a companion to VaR rather than a replacement. Our guide to 95% backtesting rules for FX VaR shows how that test works. Second, ES gives the board a more honest answer to the question "what if it goes wrong?".
How to calculate FX expected shortfall
There are three standard approaches. The IMF's 2006 paper lists them for firm FX VaR: historical simulation, variance-covariance (parametric) and Monte Carlo. ES can be taken from any of them.
Parametric ES (variance-covariance)
Parametric means you assume a distribution, usually normal, estimate volatility and correlations from market data, and compute the result from a formula. For a normally distributed loss L with mean μ and standard deviation σ, the expected shortfall at confidence level α is:
ES = μ + σ × φ(Φ⁻¹(α)) / (1 − α)
Here Φ⁻¹(α) is the point on the standard normal curve below which α of outcomes fall (1.645 at 95%, 2.326 at 99%), and φ is the standard normal density at that point. VaR under the same assumption is μ + σ × Φ⁻¹(α). Because both scale with σ, ES is a constant multiple of VaR in the parametric case, which matches the finding in the Springer chapter on managing risk with expected shortfall. That chapter also uses FX contracts as an example of a portfolio well suited to parametric analysis.
Historical simulation
Historical simulation applies your current position to past exchange-rate changes to build a loss distribution. As the IMF paper explains, you read the relevant percentile as VaR. For ES you then average all the losses beyond that percentile. With 500 daily scenarios at 97.5%, for example, you average the worst 12 or 13 outcomes. This needs no normality assumption, but it needs a large database and is computationally intensive, and the answer depends on which history you chose. Our walkthrough of daily historical VaR for FX books covers full revaluation and EWMA weighting, which makes recent volatility count for more.

Monte Carlo simulation
Monte Carlo generates thousands of random scenarios from a specified model and averages the tail. The IMF notes that it can handle any underlying distribution but is also computationally intensive. It earns its keep when the book contains options or other non-linear FX instruments, where a parametric shortcut is a poor fit. The Springer chapter makes the same distinction: FX contracts suit parametric analysis, European options suit simulation, and in the simulation case ES tends to give more robust risk estimates.
A worked example: €1 million receivable, reporting in sterling
The figures below are illustrative, not market data. Assume a UK company expects €1 million and the sterling value of the position is £1,000,000. Assume daily volatility of 0.6% and a mean daily change of zero. Then σ = £6,000.
| Confidence | z-value | Density φ(z) | VaR (1 day) | ES (1 day) | ES ÷ VaR |
|---|---|---|---|---|---|
| 95% | 1.645 | 0.1031 | £9,870 | £12,378 | 1.25 |
| 97.5% | 1.960 | 0.0584 | £11,760 | £14,026 | 1.19 |
| 99% | 2.326 | 0.0267 | £13,958 | £15,990 | 1.15 |
How to read it:
- At 99%, VaR is about £13,958. On the worst 1% of days, the average loss is about £15,990 if returns are normal.
- Moving from 95% to 99% raises ES by roughly 29% (from £12,378 to £15,990). The percentage is a depth setting for the tail, not a strictness dial.
- The ratio of ES to VaR is fixed in the parametric case, so the table adds no new information about tail shape. It only becomes informative when you compute ES by historical simulation or Monte Carlo and compare it with the parametric figure. If the simulated ES is well above the parametric one, your book has fatter tails than the normal model assumes.
To scale to a longer horizon, the usual square-root-of-time shortcut multiplies the one-day figure by the square root of the number of days, so a 10-day figure is about 3.16 times the one-day number under the same assumptions. Treat that as an approximation: it depends on returns being independent from day to day.
The inputs that move your number most
The IMF paper lists the VaR inputs for a firm's FX exposure as the holding period, the confidence level and the reporting currency, and gives one day as a typical holding period with 95% and 99% as usual confidence levels. Each deserves a decision from you, not a default.
- Holding period. Match it to how fast you can actually act. If you can adjust a hedge the same day, one day is sensible. If the exposure is a quarterly settlement you hedge once a month, a longer horizon describes your real risk better.
- Confidence level. Pick it for the decision. A 95% figure is useful for daily monitoring because breaches occur often enough to learn from. A 99% or 97.5% figure suits capital or buffer questions.
- Reporting currency. Risk is measured in the currency your accounts use. A euro exposure for a sterling reporter is not the same risk as for a euro reporter.
- Aggregation. Offsetting positions (euro receivables against euro payables) reduce the net exposure, and correlations between currencies reduce portfolio risk further. A company that computes ES currency by currency and adds the results overstates its risk.
- Volatility and correlation estimates. A long, flat average will understate risk after a regime change. Weighting recent observations more heavily, as EWMA does, reacts faster.
Limitations to know before you rely on ES
Be honest about what the number assumes.
- Parametric ES is conditional on its assumptions. The IMF identifies jointly normal returns and linear portfolio changes as the limitations of variance-covariance analysis. If you hold FX options, that linearity does not hold.
- Historical simulation depends on the window. A calm two-year window produces a calm ES.
- ES treats the tail equally. The IMF-linked paper notes that ES weights all losses beyond VaR equally, so a manager who dislikes extreme losses more than moderate ones may want a measure that reflects that preference. In practice, pair ES with named stress scenarios.
- It is a model output, not a promise. Use it to compare positions and set limits, and keep a stress view alongside it.
If your company is regulated, or has covenants tied to specific risk measures, confirm with your auditor or your bank which measures they accept. This article describes methods, not a compliance position.
From a number to a decision: using ES in hedging and limits
The point of computing ES is to change something. Three practical uses stand out for a corporate treasury.
Hedge ratio. Compare unhedged ES with the ES after a proposed forward cover. The reduction, in pounds, is the value of the hedge in risk terms, which is easier to explain to a board than a percentage. We cover this in our guide to VaR-based hedging for currency risk.
Limits and alerts. Set a VaR limit for daily monitoring and an ES ceiling that the board has approved for the worst-case average. Our piece on FX risk limits with VaR and intraday alerts walks through the mechanics.
Scenario weighting. If you suspect the recent past does not represent the risks ahead, you can weight scenarios explicitly. See scenario weighting in VaR for when that helps.
For the wider toolkit, our list of risk measurement methods shows where ES sits next to sensitivity analysis and stress testing.
Doing this in a spreadsheet, and where it strains
A parametric VaR and ES for two or three currencies fits in a spreadsheet: a covariance matrix, position vector and the formula above. Trouble starts when the position list changes daily, when you want historical and parametric figures side by side, or when several people need the same numbers and an audit trail. At that point the work becomes a recurring process. Our overview of a Value at Risk calculation workflow for FX risk lays out the steps so you can see where the time goes.
Where Corphedge fits
Corphedge is an online platform for corporate FX risk management. It offers currency position tracking, hedging strategy simulation, Value at Risk analysis, portfolio reporting, live market data and automated notifications, with operational expert advice available alongside. Our hedging based on value at risk page explains how VaR drives hedging decisions on the platform, and the platform overview shows the use cases it covers.
If your team wants to build the theory first, the FX hedging course is a one-off €220 video course on FX risk management for finance professionals.
Our view
Most finance teams we talk to about currency risk are not short of ideas. They are short of a number the whole team agrees on, refreshed often enough to act on.
That is why we start with positions and VaR: you need to know what you hold, by currency, and what a bad day looks like at a stated confidence level. Expected shortfall then answers the follow-up that every board asks: and if it is worse than that?
Our platform is built so that exposure tracking, hedging simulation, VaR analysis and reporting live in one place, with live market data and alerts, instead of in a chain of spreadsheets. Our aim is to give small and mid-sized companies analytics of the kind large institutions use, at a lower cost than traditional institutional platforms.
A risk figure only has value if it changes a hedge, a limit or a conversation. Use ES to size the tail, VaR to monitor and backtest, and scenarios to test the stories your history does not contain.
Bartas
FAQ
What is the difference between expected shortfall and VaR?
VaR is the loss threshold that should be exceeded only with a stated small probability over a given horizon. Expected shortfall is the average loss on the outcomes beyond that threshold. At the same confidence level, ES is greater than or equal to VaR.
Is expected shortfall the same as CVaR?
In most corporate and academic usage, yes: CVaR, tail VaR and expected shortfall describe the average loss in the tail beyond VaR. Some sources define them differently for discrete data, so check the definition inside any software or report you rely on.
Which confidence level should an FX team use?
The IMF paper names 95% and 99% as usual confidence levels for FX VaR. Many teams monitor daily at 95% for frequent feedback and use 97.5% or 99% for buffer and board-level questions. Choose by the decision it supports and keep it constant so results stay comparable over time.
Can I calculate expected shortfall with parametric VaR?
Yes. If you assume normal returns, ES equals the mean loss plus volatility times the normal density at the VaR point, divided by the tail probability. In that case ES is a fixed multiple of VaR, so it adds most value when you also compute it by simulation and compare the two.
Does a UK company have to use expected shortfall?
The Basel market-risk framework that uses ES applies to banks, which must hold minimum capital against market risk. A corporate treasury is not bound by it, so ES is a management choice. If lenders or auditors specify a measure, follow their requirement.
Sources
- The market risk framework in brief, Basel Committee (January 2019)
- Exchange Rate Risk Measurement and Management, IMF Working Paper 06/255 (2006)
- Risk management paper defining expected shortfall (ASECU)
- Managing Risk with Expected Shortfall (Springer)
- Expected shortfall: normal distribution formula