
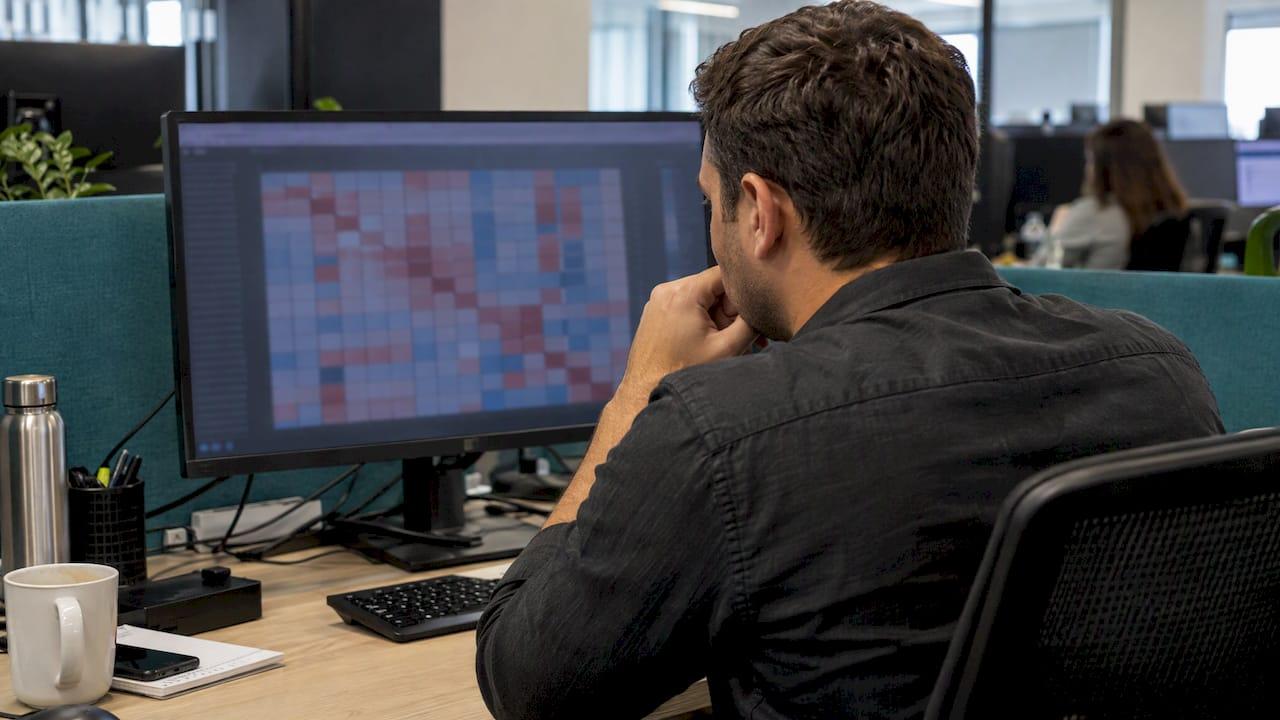
An FX correlation matrix is a grid that shows how closely currency pairs have moved together over a chosen window. Each cell holds a coefficient between −1.00 and +1.00. For a finance team, the grid answers one practical question: are your currency exposures really separate bets, or one position in disguise? This guide covers how the numbers are calculated, how to read them, which data and window to choose, and where the matrix stops being reliable.
TL;DR
- A matrix shows the correlation between each pair in its row and column; the diagonal is always +1.00.
- Calculate on returns, not price levels, and always state the window, bar interval and return method next to the result.
- Correlation is backward-looking and linear. Treat it as risk context for exposure and hedge decisions, not a forecast.
- For corporates, the value lies in measuring exposure at portfolio level: offsetting positions can lower net risk, but only while the relationship holds.
- Check any data source for timestamps, latency, coverage and licensing before relying on its numbers.
Table of Contents
- What an FX correlation matrix shows
- How to read the numbers
- Choosing the window and data frequency
- What data you need for a current matrix
- Choosing real-time FX data and streaming quotes
- How often to refresh, and how to sanity-check
- Where correlation fits in corporate risk management
- Perspective
- See your correlations next to your exposures
- FAQ
- Sources
What an FX correlation matrix shows
Picture a table with the same currency pairs down the side and across the top. Each cell shows the correlation between the row pair and the column pair. A pair against itself is always +1.00, so the diagonal is fixed, and the grid mirrors itself on both sides of it.
The coefficient is usually Pearson's. It is the covariance of two return series divided by the product of their standard deviations. Three anchor values matter:
- +1.00: perfect positive co-movement over the sample.
- 0.00: no linear relationship.
- −1.00: perfect inverse co-movement.
A common rule of thumb treats values above +0.7 or below −0.7 as strong, 0.4 to 0.7 as moderate, and anything between −0.4 and +0.4 as weak or negligible. These are conventions, not laws, and different tools draw the lines differently.
Why returns, not prices
Raw exchange rates trend, so correlating price levels produces impressively high numbers that mostly reflect shared trends rather than day-to-day co-movement. The day-to-day behaviour is what decides whether two open positions hurt you on the same morning.
The standard fix is to convert rates to log-returns, log(P(t)/P(t−1)), and correlate those. One public methodology note describes this step because raw FX rates are non-stationary and then applies a rolling window, 90 days by default.
How to read the numbers
Take the example of one month of data: EUR/USD and GBP/USD showed a correlation of 0.95, while EUR/USD and USD/CHF showed −1.00. In plain terms, a long position in both EUR/USD and GBP/USD is close to one bet, not two. Going long EUR/USD and short USD/CHF would have been nearly the same bet too, because the negative correlation turns one into a mirror of the other.
OANDA's description of its tool is useful here: strongly positively correlated open positions expose you to higher risk, while strongly negatively correlated ones are in most situations more risk-averse. That is the trading view. A treasury view differs slightly, because a company's positions are commercial cash flows, not speculative trades.
A treasury reading
A company with a euro-earning subsidiary and a sterling-losing one may carry a small net exposure when the two currencies move together. University lecture notes on hedging make this point: because currencies are correlated, firms look at exposure at portfolio level, and a high positive GBP-EUR correlation can leave the net total exposure very low.
The reverse also holds. The same notes warn that non-matching exposures in currencies with negative correlation are very dangerous, because the moves compound instead of offsetting.
| Coefficient | What it suggests | What a treasury team might do |
|---|---|---|
| +0.7 to +1.00 | Pairs moved together | Treat as largely one exposure; check for double-counting |
| +0.4 to +0.7 | Moderate co-movement | Partial offset only; size hedges separately |
| −0.4 to +0.4 | Weak or no linear link | Do not assume offset or confirmation |
| −0.7 to −1.00 | Pairs moved in opposition | Check whether offsetting exposures actually exist |
A reading near zero is not proof of independence. Pearson's coefficient measures linear association and does not capture nonlinear dependence or tail behaviour. Two pairs can show a low coefficient and still share the same macro catalyst.
Choosing the window and data frequency
The same pair of currencies can give very different coefficients depending on the setup. Matrices are built from five-minute, one-hour or daily closes, with lookbacks from about 24 hours to a year. Short windows react faster but carry more noise. Long windows smooth out short swings but can dilute a new relationship.

How much difference does it make? A Goldman Sachs risk paper showed that, with a 100-day rolling window, French and German 10-year bond return correlation ranged between 0.37 and 0.82, against a constant 0.57 from the full history. That is a bond example, not currencies, but the lesson transfers: one number hides a moving relationship. The same paper describes exponential weighting, where each day back gets 90% of the weight of the day after it, so recent data counts more.
Practical settings for a finance team
- Use daily closes for exposure work. Hedging decisions run over weeks and months, so intraday noise adds little.
- Compare at least two windows. Look at 30 days and one year side by side. Correlation tends to rise under extreme stress, exactly when diversification matters most.
- Keep enough observations. One tutorial suggests at least 30 data points, ideally 60 to 100 or more, with the same date range and aligned closes for every pair.
- Fix the method. A reading is only comparable with another if return method, bar interval, sample window and timestamp treatment match.
If you want to think harder about how the observation window changes what you conclude, choosing a timeframe without fooling yourself walks through the trade-offs.
Tools differ more than their labels suggest. OANDA's matrix, for instance, uses a fixed one-year period and the New York close at 5:00 PM ET. Another provider's "90-day" setting may use different data. The advice from one practitioner site is to inspect the actual pair list, data source, return convention and window rather than assume similar names mean identical inputs.

What data you need for a current matrix
A matrix is only as good as its inputs. A typical public methodology uses completed daily midpoint closes across 28 major crosses, and requires at least 40 valid closes from the latest 50 candles before a pair is included. Another approach computes daily log returns aligned over common trading days, which avoids comparing a Tuesday close in one series with a Wednesday close in another.
A few mechanics matter for treasury use:
- Same calendar. Delete dates missing from any series before computing.
- Same cut-off time. Mixing London and New York closes quietly changes the answer.
- Same return type. Simple and log returns are close for small moves, but mixing them inside one matrix is an error.
Choosing real-time FX data and streaming quotes
For a historical matrix, end-of-day data is enough. For live exposure monitoring, you need a feed. A vendor checklist suggests asking whether prices are real or calculated, how many sources feed each pair, and what the tick rates and spreads look like in quiet hours. It also points to timestamp meaning and precision, stale-price handling, latency under load, and licensing for storing, displaying and analysing data.
Two details deserve your attention:
- Timestamps. The MiFIR clock-accuracy rule applies to trading venues and their members, not to data vendors. What you need is a timestamp you can line up against your own records, and a statement of whether it marks when the bank created the price or when the vendor received it.
- Latency and delay. For a streaming feed, one provider guide advises latency well under a second from receipt to client, and warns that exchange data is often delayed around 15 minutes unless you hold the right to show it live. Ask which data is real-time and which is delayed, and how the delay is marked.
| Check | Question to ask |
|---|---|
| Price type | Executable, indicative or calculated? |
| Coverage | How many contributing sources per pair? |
| Timestamps | Bank-created or vendor-received? Precision? |
| Latency | What is the stated delay at peak load? |
| Stale prices | How are they flagged or filtered? |
| Licensing | May you store, display and analyse the data internally? |
How often to refresh, and how to sanity-check
Because correlations shift with global conditions, data should be updated regularly. Investopedia names the usual drivers: diverging monetary policy, commodity sensitivity, and country-specific economic and political events. For a treasury, a sensible rhythm is monthly for a standing review, and ad hoc after a central-bank repricing or a market shock.
Validation steps that work without special software:
- Recompute two or three pairs by hand in a spreadsheet and compare with the tool.
- Confirm the diagonal reads +1.00 and the grid is symmetric.
- Check that obvious relationships, such as EUR/USD and GBP/USD, look plausible for the period.
- Re-run with a second window. If the picture flips, treat the relationship as unstable.
The Bank of England's research shows why stability cannot be assumed. A staff working paper found asymmetric correlations in currency markets: high-interest-rate currencies had a correlation with the world market about two times larger in bear equity regimes than in normal ones. A matrix built in calm months can understate co-movement in a sell-off.
Where correlation fits in corporate risk management
Correlation feeds the covariance matrix behind Value at Risk. The IMF's working paper on exchange rate risk notes that the variance-covariance approach assumes returns are jointly normal and the position is linearly dependent on them. It also notes that firms usually add operational limits, such as nominal amounts or stop-loss orders, on top of VaR limits.
Some corporates use hedge optimization to reduce the number of hedge transactions based on the exposure portfolio's value at risk, with the caveat that past correlations may not hold. In practice, that means using the matrix to set priorities and hedge ratios, then pairing it with policy limits and scenario tests.
For a deeper treasury walk-through, see our guide on using currency correlation to set VaR-backed hedge ratios, and our practical piece on multi-currency hedging for finance teams. If volatility is the missing half of the picture, FX volatility explained covers it.
Perspective
We see the same pattern in many finance teams: a correlation grid is open in a spreadsheet, but the exposures sit in another file, and the hedge ratios in a third. The matrix is only useful when it meets the exposure.
That is why we built Corphedge around one view of positions, live market data, Value at Risk and reporting. Correlation then becomes an input to a hedging decision, not a chart to admire. We designed the platform for SMEs that want enterprise-grade analytics without institutional-platform costs.
Our advice is simple: measure at portfolio level, compare windows, document your method, and review it on a schedule. Our operational expert advice exists for the moments when the numbers disagree with each other.
Bartas
See your correlations next to your exposures
Corphedge is an online platform for corporate FX risk management. It brings together currency position tracking, hedging strategy simulation, Value at Risk analysis, portfolio reporting and live market data in one place, with automated notifications and operational expert advice available alongside. See how it works on the Corphedge platform page, or read how we approach hedging based on value at risk.
We are also expanding to Poland and Sweden, so teams with zloty or krona exposure can follow the same portfolio approach. If you want the underlying skills, our FX hedging course is a one-off 220 EUR.
FAQ
What is the difference between a currency correlation matrix and a forex correlation matrix?
None in substance. Both terms describe a grid of correlation coefficients between currency pairs. Differences come from the inputs: the pair list, window, data frequency and return method.
What window should I use for an FX correlation matrix?
There is no universal answer. No single window is a sufficient sample or proof of the current regime, so compare a short one, such as 30 days, with a longer one, such as a year, and note any gap between them.
Can I rely on a correlation of 0.9 to offset exposures?
Not by itself. Values like 0.70 or 0.85 do not turn exposures into one identical position. Use correlation to size and prioritise hedges, and keep limits and scenario tests in place.
Do I need real-time data for a correlation matrix?
Not for a standard review, where daily closes are sufficient. Real-time or streaming quotes matter for live exposure monitoring, where timestamps, latency and licensing terms become the main checks.
Sources
- Correlation Indicators, FX Foundations
- FX Correlation Algorithms
- Calculating Currency Correlation Matrix Models for FX Risk
- Forex Correlation Matrix (30, 90 & 365 Day), Economicium
- Mastering Currency Correlations, Investopedia
- Correlation: heatmap and matrix, OANDA
- Hedging FX Risk, University of Houston
- Measuring transaction exposure, University of Houston
- Forex Correlation Risk Methodology: 50-Day Matrix
- Risk Management Series, Goldman Sachs
- How to Calculate Currency Correlations Using Excel
- Currency pair correlations in practice
- FX Correlation Matrix API
- FX Market Data RFP Checklist 2026
- How to choose a market data provider
- Bank of England Staff Working Paper No. 533
- IMF Working Paper 06/255
- Why FX hedge metrics matter, Euromoney